

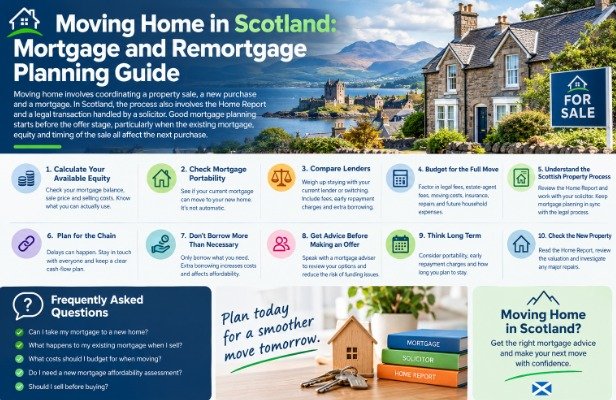
Moving home involves coordinating a property sale, a new purchase and a mortgage. In Scotland, the process also involves the Home Report and a legal transaction handled by a solicitor. Good mortgage planning starts before the offer stage, particularly when the existing mortgage, equity and timing of the sale all affect the next purchase.
Calculate your available equity
Start with an up-to-date mortgage balance or redemption figure and a realistic estimate of the sale price. Allow for selling costs and any early repayment charge. The remaining amount is the equity available toward the next purchase. Avoid assuming that an optimistic sale price will be achieved if the new purchase depends on the proceeds.
Check whether your mortgage is portable
Some mortgages include portability, which may allow the existing product to move to a new property subject to the lender’s conditions. Portability is not automatic approval of the new purchase. The new property, affordability and any additional borrowing may still need to meet the lender’s criteria. Check the product terms early.
Compare staying with the lender and switching
If the current mortgage is portable, compare that option with arranging a new mortgage. A new mortgage can have different rates and features, while keeping an existing deal may have benefits depending on its terms. The comparison should include early repayment charges, fees and the amount of additional borrowing required.
Budget for the full move
Moving costs can include legal fees, estate-agent fees, mortgage fees, removals, insurance, repairs and property transaction taxes where applicable. Keep a reserve for expenses after completion. A larger home may also bring higher council tax, energy and maintenance costs, so compare the ongoing household budget as well as the purchase price.
Understand the Scottish property process
The Home Report provides important information about many Scottish properties. Buyers should read the survey and valuation, property questionnaire and energy report. Your solicitor can advise on the legal aspects of making an offer and concluding the transaction. Mortgage planning should run alongside that legal process.
Plan for the chain
A sale and purchase may depend on other transactions completing. Delays can create temporary accommodation needs or overlapping costs. Keep the estate agent, solicitor, lender and mortgage adviser informed if the timing changes. A clear cash-flow plan can help you understand how much flexibility you have.
Do not borrow more than necessary
If the new home requires additional borrowing, calculate the exact amount needed. Extra borrowing increases the mortgage balance and can affect affordability and long-term interest. Home improvements can also be funded in different ways, so compare the costs before adding them to the mortgage.
Get advice before making the offer
Prestige Mortgage Solutions Ltd can help homeowners review the mortgage side of a move from Glasgow, East Kilbride and across the wider UK. Understanding the current mortgage, equity and potential new borrowing before making an offer can reduce the risk of discovering a funding issue later.
Coordinate the transaction
Keep your solicitor, estate agent and mortgage adviser informed about material changes. If the purchase price, sale price or employment circumstances change, the financing may need to be reviewed. Early communication is easier than dealing with a problem immediately before completion.
Think about future flexibility
If you expect to move again, review mortgage features such as portability and early repayment charges. If you expect to stay for a long time, the interest rate and overall cost may be more important. Match the product to the expected holding period.
Check the new property’s information
A new property should be assessed on its own merits. Read the Home Report, understand the valuation and investigate significant repair recommendations. A lender’s valuation and the property’s condition are separate considerations.
Understand temporary finance needs
If the sale and purchase do not complete together, temporary accommodation, storage or overlapping property costs may arise. A cash-flow plan can show how long the household could manage under different completion dates.
Allow for changes in the sale price
The equity available for the next purchase depends on the actual sale proceeds, not simply an initial valuation. If the final sale price is lower than expected, the deposit for the new home may be smaller. Build some margin into the plan where possible.
Review the plan after moving
Once the move is complete, review the new mortgage terms, direct debit, insurance and household budget. Keep the next mortgage review date in your calendar so that future refinancing does not become a last-minute task.
Keep the mortgage team updated
If the purchase price, sale price, employment or borrowing requirements change, tell your mortgage adviser and lender promptly. Updated information may change the affordability or product assessment.
Prepare for delays
Property transactions do not always complete on the original timetable. Consider what you would do if the sale or purchase is delayed. Temporary accommodation, storage or overlapping costs can affect the cash required.
Think about the new monthly payment
Moving to a larger or more expensive property can increase the mortgage payment and other household costs. Calculate the full expected monthly budget before making an offer. Include council tax, utilities, insurance and maintenance.
Use a realistic sale-price estimate
The amount available for the next deposit depends on the final sale price. Speak with an appropriate property professional and avoid building the new purchase around an optimistic figure. A conservative estimate can reduce the risk of a funding shortfall.
Check your mortgage before listing the property
Before putting your current home on the market, confirm the mortgage balance, product end date, early repayment charge and portability terms. Knowing these details helps you understand how the sale will interact with the next mortgage.
Keep a post-move reserve
The first months after moving can involve more spending than expected. Keep a reserve for repairs, furniture, appliances and other household costs. Avoid using every pound of equity as a deposit if doing so leaves the household financially exposed.
Think about the next mortgage review
When arranging a mortgage for the new home, note the end date of the initial deal and the likely point at which you should begin reviewing alternatives. This is particularly important if you have a fixed rate. Early planning can provide time to compare a product switch and remortgage rather than waiting until the rate has already ended.
Compare the cost of moving with staying
Moving home can be expensive, so compare the financial impact with the cost of remaining in the current property. Staying may require repairs or improvements, while moving can involve transaction and mortgage costs. A side-by-side comparison can make the decision more objective.
Think about the wider cost of a larger home
A larger property can mean higher heating, insurance, council tax and maintenance costs. When comparing properties, add these expected costs to the new mortgage payment. This gives a more realistic picture of the move. A home should fit both the purchase budget and the ongoing household budget.
Check the new mortgage before making a binding offer
If the new property requires a larger mortgage, obtain a realistic affordability assessment before committing to a purchase. An agreement in principle can help establish a potential borrowing range, although it is not a final mortgage offer. If the purchase price changes, update the calculation rather than assuming the original figures still apply.
Keep the move aligned with your long-term plans
A move is often made because the household needs more space, a different location or a change in lifestyle. The mortgage should support that goal rather than create unnecessary financial pressure. Consider how long you expect to remain in the new home, whether the mortgage features match that timeframe and how much flexibility you want if circumstances change.
Frequently Asked Questions
Can I take my mortgage to a new home?
Some mortgages are portable, subject to the lender’s terms and approval. The new property and any additional borrowing may still need to satisfy lender criteria.
What happens to my existing mortgage when I sell?
Usually the mortgage is redeemed from the sale proceeds unless a suitable porting arrangement is approved. Check the lender’s exact terms.
What costs should I budget for when moving?
Consider legal, estate-agent, mortgage, moving, insurance, repair and applicable property transaction costs.
Do I need a new mortgage affordability assessment?
If you arrange new borrowing or change lender, affordability and underwriting requirements may apply.
Should I sell before buying?
The right sequence depends on your finances and circumstances. Compare the cash-flow risks of selling first and buying first.
Conclusion
Mortgage decisions are easier to manage when the full financial picture is understood before an application is made. For readers considering moving home mortgage Scotland, preparation should focus on genuine affordability, lender criteria, property information and the long-term cost of the borrowing. Professional advice can help explain the available routes, but the final decision should always reflect the borrower’s own circumstances and the terms of the mortgage offered.
